
Choosing a credit card in 2026 isn’t simply about finding the card with the highest cashback percentage.
One card may be excellent for Amazon shopping. Another may save more on Flipkart or Myntra. A travel card may offer valuable lounge access, while a fuel card can make more sense for someone who drives every day.
And then there are cards with no annual fee, premium cards with expensive fees, reward cards, secured cards and cards designed around specific spending habits.
So which one is actually right for you?
That’s what this guide is designed to answer.
Credit card usage in India has grown rapidly as consumers increasingly use cards for online shopping, travel, dining, subscriptions and everyday payments. But more choices also mean more confusion.
At Prabooz, we don’t want to simply give you a list of popular cards.
We’ll help you compare them side-by-side, understand the real benefits and limitations, and identify which card may suit your spending pattern.
Quick answer: There is no single “best credit card” for every Indian customer. The best card is the one that gives you useful rewards and benefits on spending you already do — without unnecessary fees or debt.
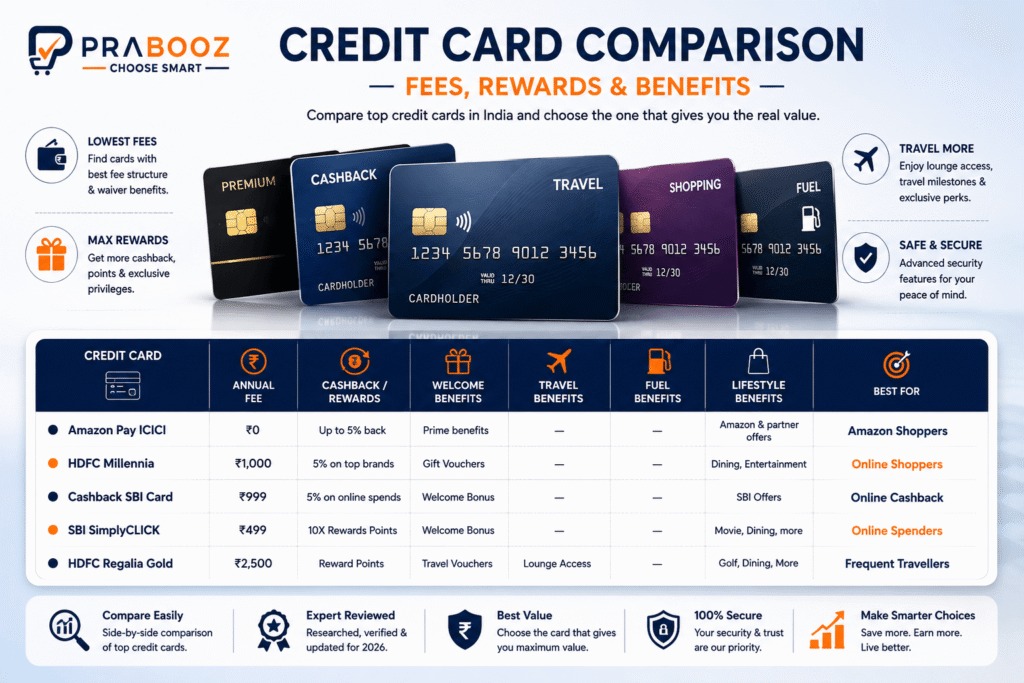
Comparison Table
The detailed reviews below will help you understand those differences before you decide.
Card Type Annual Fee (as of Aug 2026)* Best For View Details Buy Online HDFC Millennia Cashback ₹1,000+ Online shoppers View Details → Buy Online → CASHBACK SBI Cashback ₹999+ Regular online shoppers View Details → Buy Online → Amazon Pay ICICI Cashback ₹0 Amazon & everyday spending View Details → Buy Online → SBI SimplyCLICK Rewards ₹499+ Online shoppers View Details → Buy Online → HDFC Diners Club Rewardz Credit Card Rewards ₹1,000+ Regular reward-point spenders View Details → HDFC Regalia Gold Travel ₹2,500+ Frequent travellers View Details → Buy Online → Amex Platinum Travel Travel ₹5,000+ Travel & milestone spenders View Details → Buy Online → SBI Miles ELITE Travel ₹4,999+ Frequent flyers View Details → Buy Online → BPCL SBI Fuel ₹499+ Fuel spending View Details → Buy Online → IDFC FIRST WOW Secured ₹0 New-to-credit users View Details → Buy Online → Axis Insta Easy Secured ₹0 Credit-building View Details → Buy Online → HDFC Infinia Premium ₹12,500+ High spenders View Details → Buy Online → SBI ELITE Premium ₹4,999+ Premium rewards View Details → Buy Online → American Express Platinum Premium ₹66,000+ Premium travel & lifestyle View Details → Buy Online →
Annual fees, rewards, benefits and eligibility criteria are based on information available as of August 2026. Credit card terms can change, so always check the issuer’s latest terms and conditions before applying.
Our Quick Picks for 2026
Choosing the right credit card starts with understanding what you actually want from it.
Some people want cashback on everyday purchases. Others spend heavily on Amazon, Flipkart or other online platforms. Frequent travellers may care more about airport lounge access and travel rewards, while daily commuters may get more value from fuel-related benefits.
There are also cards designed for people building their first credit history, as well as premium cards aimed at customers with higher spending levels.
That’s why we haven’t selected a single card and called it “the best credit card in India.” Instead, we’ve picked leading options across different categories and spending needs.
🛒 Cashback & Everyday Spending
HDFC Millennia Credit Card
A strong option to compare if a large part of your spending is on popular online merchants and everyday digital purchases.
Cashback SBI Card
Worth considering if you prefer a straightforward cashback-focused card for eligible online and offline spending.
Amazon Pay ICICI Bank Credit Card
A particularly interesting option for Amazon users, especially because of its lifetime-free structure and Amazon-focused rewards.
Best suited for: Online shopping, everyday spending and customers who prefer cashback over complicated reward systems.
🎁 Rewards & Online Shopping
SBI SimplyCLICK Credit Card
Designed with online shopping in mind, with accelerated rewards on selected online partners.
Flipkart Axis Bank Credit Card
A strong candidate for shoppers who regularly use Flipkart and Myntra and want shopping-focused cashback.
HDFC Millennia Credit Card
Another card worth comparing for online shopping, particularly where its eligible merchant categories match your spending.
Best suited for: Frequent online shoppers who want to earn value from purchases they already make.
✈️ Travel & Lifestyle
HDFC Regalia Gold Credit Card
A popular premium-category option to consider for travel, lounge access, rewards and lifestyle benefits.
American Express Platinum Travel Credit Card
Designed around milestone-based rewards and travel benefits, making it more interesting for customers who can reach its spending milestones.
MakeMyTrip ICICI Bank Credit Card
Worth considering for people who frequently book flights, hotels and other travel through MakeMyTrip.
SBI Card ELITE
A premium lifestyle and travel-focused option for customers looking beyond basic cashback.
SBI Card Miles ELITE
Designed more specifically around travel rewards and frequent flyers.
Best suited for: Frequent travellers who can actually use travel rewards, lounge access and milestone benefits.
⛽ Fuel & Daily Commuting
BPCL SBI Card
A card worth comparing if BPCL is your regular fuel station and you spend consistently on fuel.
IndianOil ICICI Bank Credit Card
A useful option to investigate for customers who regularly fill up at IndianOil outlets.
Best suited for: Daily commuters and customers with predictable fuel spending.
🏦 Secured & Credit-Building Cards
Not everyone has a long credit history or a high income.
For customers who are new to credit, an FD-backed secured credit card can be an alternative worth considering.
Examples include:
- IDFC FIRST WOW Credit Card
- Axis Bank Insta Easy Credit Card
- Other eligible FD-backed cards available from Indian issuers
These cards are different from conventional unsecured cards because the credit facility is linked to a fixed deposit or similar security arrangement.
Best suited for: New-to-credit customers and people looking for a secured route to establishing a credit history.
Important: A secured card should not be treated as a shortcut to borrowing more. The same responsible repayment habits still matter.
💎 Premium Credit Cards
For high-spending customers, the question isn’t simply “How much cashback can I get?”
Premium cards can combine rewards with airport lounges, travel privileges, milestone benefits, concierge services and lifestyle benefits.
Cards worth comparing include:
HDFC Infinia Metal Edition
A high-end card aimed at customers with significant spending and premium travel/reward requirements.
SBI Card ELITE
A premium lifestyle card combining travel and other premium benefits.
American Express Platinum Card (Charge Card)
A luxury-focused charge card for customers who value premium travel and lifestyle privileges.
Best suited for: High spenders who can genuinely extract enough value from premium benefits to justify the fees and eligibility requirements.
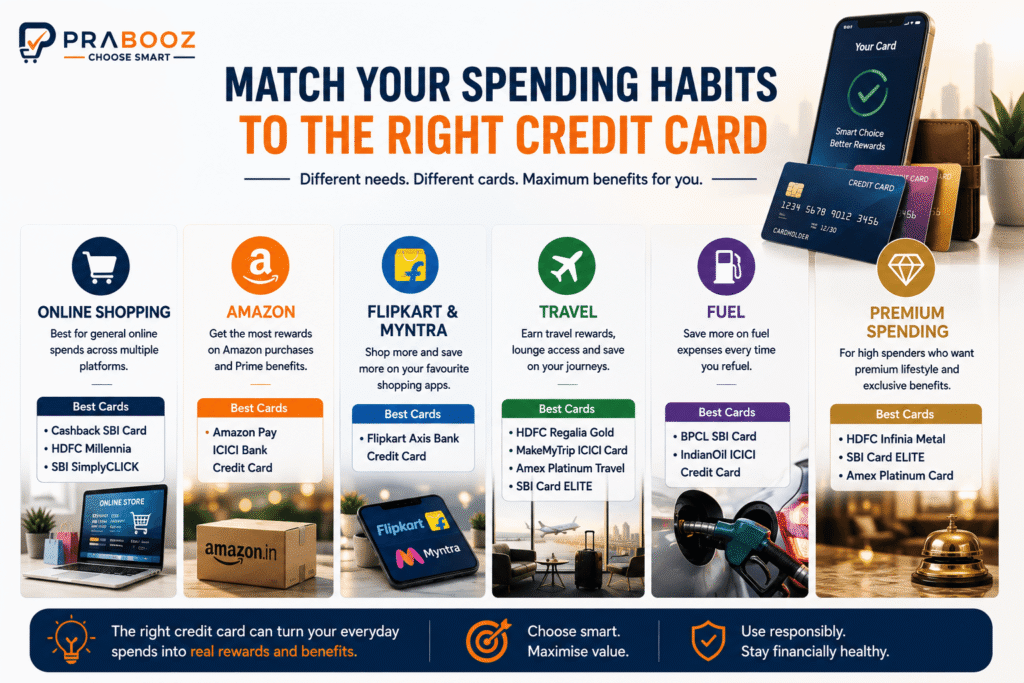
At a Glance: Our Categories
| Category | Cards Worth Comparing |
|---|---|
| Cashback | HDFC Millennia, Cashback SBI, Amazon Pay ICICI |
| Online Shopping & Rewards | SBI SimplyCLICK, Flipkart Axis, HDFC Millennia |
| Travel & Lifestyle | HDFC Regalia Gold, Amex Platinum Travel, MakeMyTrip ICICI, SBI ELITE, SBI Miles ELITE |
| Fuel | BPCL SBI, IndianOil ICICI |
| Secured / Credit Building | IDFC FIRST WOW, Axis Insta Easy and other FD-backed cards |
| Premium | HDFC Infinia Metal, SBI ELITE, American Express Platinum Card |
One important point before you compare
This list is not a ranking from #1 to #20.
A card that is excellent for a frequent Amazon shopper may be a poor choice for someone who spends most of their money on fuel. Similarly, a premium travel card can offer impressive benefits but may make little financial sense for someone who rarely travels.
That’s why the next step is a side-by-side comparison.
We’ll look at the fees, rewards, benefits and best-use cases together before moving into the detailed reviews.
💡 PRABOOZ INSIGHT
Don’t choose a credit card because it looks impressive. Choose the one whose benefits match your actual spending.
💡 PRABOOZ INSIGHT
The right card isn’t necessarily the one offering the biggest reward percentage. It is the one that gives you the most useful value for the money you already spend..
Cashback & Everyday Spending Cards
If most of your spending goes toward online shopping, subscriptions, utility payments and everyday purchases, cashback-focused cards can be a practical place to start.
We will compare cards such as:
- HDFC Millennia Credit Card
- Cashback SBI Card
- SBI SimplyCLICK Credit Card
- Amazon Pay ICICI Credit Card
- Other relevant cashback-focused options where appropriate
Top Credit Cards by Category
Choosing a credit card becomes much easier when you start with how you actually spend your money rather than simply looking for the card with the highest reward rate.
A card that works well for online shopping may not be the best choice for frequent travellers. Similarly, a premium travel card may offer excellent benefits but make little sense if you rarely travel.
That’s why we’ve grouped the cards in this guide into six practical categories. This lets you quickly identify the cards worth considering based on your spending pattern, lifestyle and financial needs.
💡 PRABOOZ INSIGHT
The “best” credit card is not necessarily the card with the highest rewards. It is the card that gives you the most useful value after considering fees, spending requirements, benefits and your ability to repay the balance on time.
1.Best Cashback Credit Cards
Cashback cards are designed for people who prefer simple, straightforward savings rather than managing complicated reward-point systems.
They can be particularly useful for regular online purchases, everyday spending and eligible transactions where cashback rates are attractive.
Cards to consider:
- HDFC Millennia Credit Card
- Cashback SBI Card
- Amazon Pay ICICI Credit Card
- Other suitable cashback-focused cards
Best for: Everyday spenders, online shoppers and customers who prefer direct cashba
2. Best Rewards Credit Cards
Rewards cards can be a better fit for customers who spend regularly and want to accumulate points that can later be redeemed for vouchers, products, travel or other benefits.
The important thing is to compare the actual value of the rewards rather than simply looking at the number of points offered.
Cards to consider:
- SBI SimplyCLICK
- HDFC reward-focused cards
- Other suitable rewards cards
Best for: Frequent spenders who are comfortable managing reward points and redemption options.
3. Best Travel Credit Cards
For frequent travellers, a travel-focused credit card can provide benefits that go beyond ordinary rewards.
Depending on the card, these may include airport lounge access, travel rewards, milestone benefits and other travel-related privileges.
Cards to consider:
- HDFC Regalia Gold
- American Express travel-focused cards
- SBI travel-focused cards
- Other suitable travel cards
Best for: Frequent domestic and international travellers who can make meaningful use of travel benefits.
4. Best Fuel Credit Cards
If fuel purchases make up a significant part of your regular expenses, a fuel-focused card may help reduce eligible fuel costs through rewards or surcharge-related benefits.
However, the value depends heavily on where you purchase fuel, how much you spend and the card’s specific conditions.
Cards to consider:
- BPCL SBI Card
- IndianOil ICICI Credit Card
- Other suitable fuel cards
Best for: Regular commuters and customers with consistently high fuel expenditur
5. Best Secured Credit Cards
Secured credit cards are different from conventional cards because they are generally backed by a fixed deposit or similar security arrangement.
They can be worth considering for people who may have limited credit history or want a more accessible way to begin building responsible credit habits.
Cards to consider:
- IDFC FIRST WOW
- Axis Insta Easy
- Other suitable secured-card options
Best for: New-to-credit customers and people looking for a card backed by a fixed deposit.
6. Best Premium Credit Cards
Premium cards are designed for customers who can justify higher fees in exchange for premium travel, lifestyle, rewards and concierge-style benefits.
These cards can offer substantial value for the right user, but paying a high annual fee simply for a prestigious card may not make financial sense.
Cards to consider:
- HDFC Infinia Metal
- SBI Card ELITE
- American Express Platinum cards
- Other suitable premium cards
Best for: High spenders and customers who can genuinely use premium benefits enough to offset the cost.
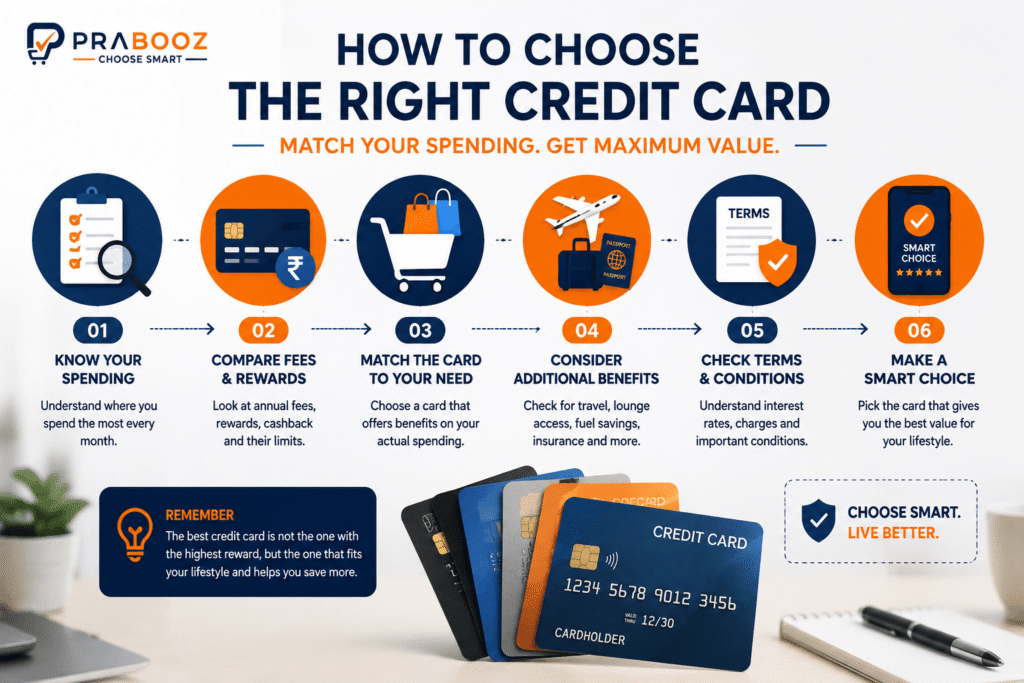
How to Choose the Right Credit Card in India
The best credit card isn’t necessarily the one with the highest cashback, the biggest welcome offer or the most premium-looking benefits. It is the card that fits your actual spending pattern and financial habits.
Before applying, ask yourself a few simple questions.
Start With Your Spending Pattern
Look at where most of your monthly credit-card spending is going.
- Mostly online shopping? A cashback or shopping-focused card may offer better value.
- Frequent travel? Look for travel rewards, lounge access and milestone benefits.
- High fuel spending? A fuel card may make more sense.
- Regular everyday spending? A simple cashback or rewards card can be practical.
- High monthly spending? Premium cards may become worthwhile if their benefits justify the annual fee.
- New to credit? An FD-backed secured card may be worth considering.
Compare the Annual Fee With the Real Value
A card isn’t automatically better because it offers more rewards.
If a card charges ₹2,000 a year but you can realistically earn only ₹1,000 worth of benefits, it may not be a good deal for you.
On the other hand, a frequent traveller may easily recover a higher annual fee through lounge access, travel rewards and milestone benefits.
Always compare the value you can actually use with the cost of holding the card.
Look Beyond the Headline Reward Rate
A “5% cashback” or “10X rewards” headline can look impressive, but the details matter.
Check:
- Which merchants qualify?
- Are there monthly or transaction-level caps?
- Are certain categories excluded?
- What is the redemption value?
- Are there minimum spending requirements?
- Does the reward expire?
- Is there a separate redemption or processing fee?
The effective value of the reward is more important than the headline percentage.
Consider Your Lifestyle
Your lifestyle can make one card far more useful than another.
Someone who travels several times a year may benefit from lounge access and travel rewards. Someone who rarely flies may get much more practical value from cashback on everyday spending.
Likewise, a card designed around fuel purchases may be useful to a daily commuter but largely irrelevant to someone who works from home.
Check Eligibility Before Applying
Credit-card approval depends on factors such as the issuer’s eligibility requirements, income, credit profile and other internal criteria.
Don’t apply for multiple cards blindly just because they look attractive.
Check the issuer’s current eligibility requirements first.
Think About Repayment, Not Just Rewards
This is perhaps the most important consideration.
Credit-card rewards are useful only when you manage the card responsibly. Carrying a balance and paying high interest can quickly wipe out the value of cashback or reward points.
If you cannot comfortably repay your purchases, a higher reward rate should not be the deciding factor.
💡 PRABOOZ INSIGHT
The smartest credit-card strategy isn’t to earn the maximum number of rewards. It’s to earn useful rewards without paying unnecessary fees or interest.
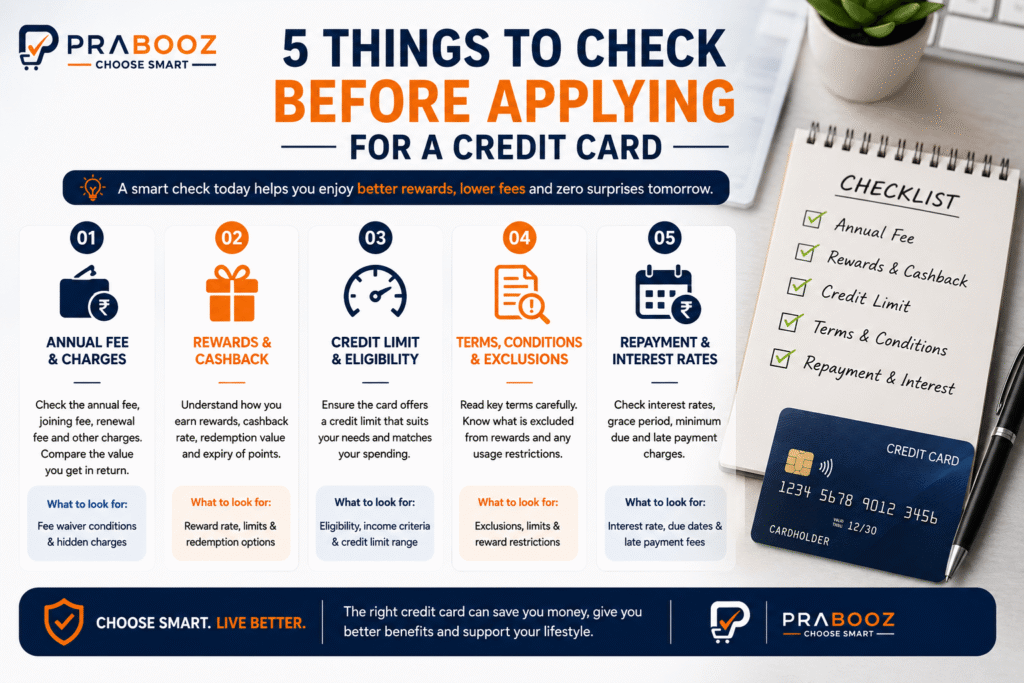
What to Check Before Applying for a Credit Card
Finding a card that matches your spending is only the first step. Before you click “Apply”, take a few minutes to check the card’s costs, reward rules, eligibility requirements and repayment conditions.
A card can look attractive at first glance but become less valuable when you consider annual fees, reward limits, exclusions or other charges.
Use this checklist before making your decision.
1. Annual Fee & Other Charges
Check the joining fee, annual or renewal fee and other applicable charges before applying.
Also look for fee-waiver conditions. A card may have an annual fee that can be waived if you meet a particular spending requirement.
What to check:
- Joining fee
- Annual/renewal fee
- Fee-waiver conditions
- Other applicable charges
2. Rewards & Cashback
Don’t judge a card only by its advertised cashback or reward rate.
Check where you actually earn the rewards, whether there are spending limits, how rewards are redeemed and whether points have an expiry period.
What to check:
- Reward or cashback rate
- Eligible spending categories
- Reward limits
- Redemption value and options
- Expiry conditions
3. Credit Limit & Eligibility
Before applying, make sure you meet the issuer’s current eligibility requirements.
Your approved credit limit may also differ from what you expect, so don’t choose a card simply because it advertises attractive benefits.
What to check:
- Income requirements
- Age and other eligibility criteria
- Credit profile requirements
- Expected credit-limit range, where disclosed
4. Terms, Conditions & Exclusions
This is one of the easiest areas to overlook.
Read the important terms to understand which transactions qualify for rewards and which are excluded, along with spending limits, restrictions and other conditions.
A high reward rate is less useful if most of your regular spending falls outside the eligible categories.
5. Repayment & Interest Rates
Finally, understand what happens if you don’t pay the full amount due.
Check the applicable interest rate, payment due date, minimum amount due and late-payment charges.
If possible, treat your credit card as a payment tool rather than extra income and aim to pay the full bill on time.
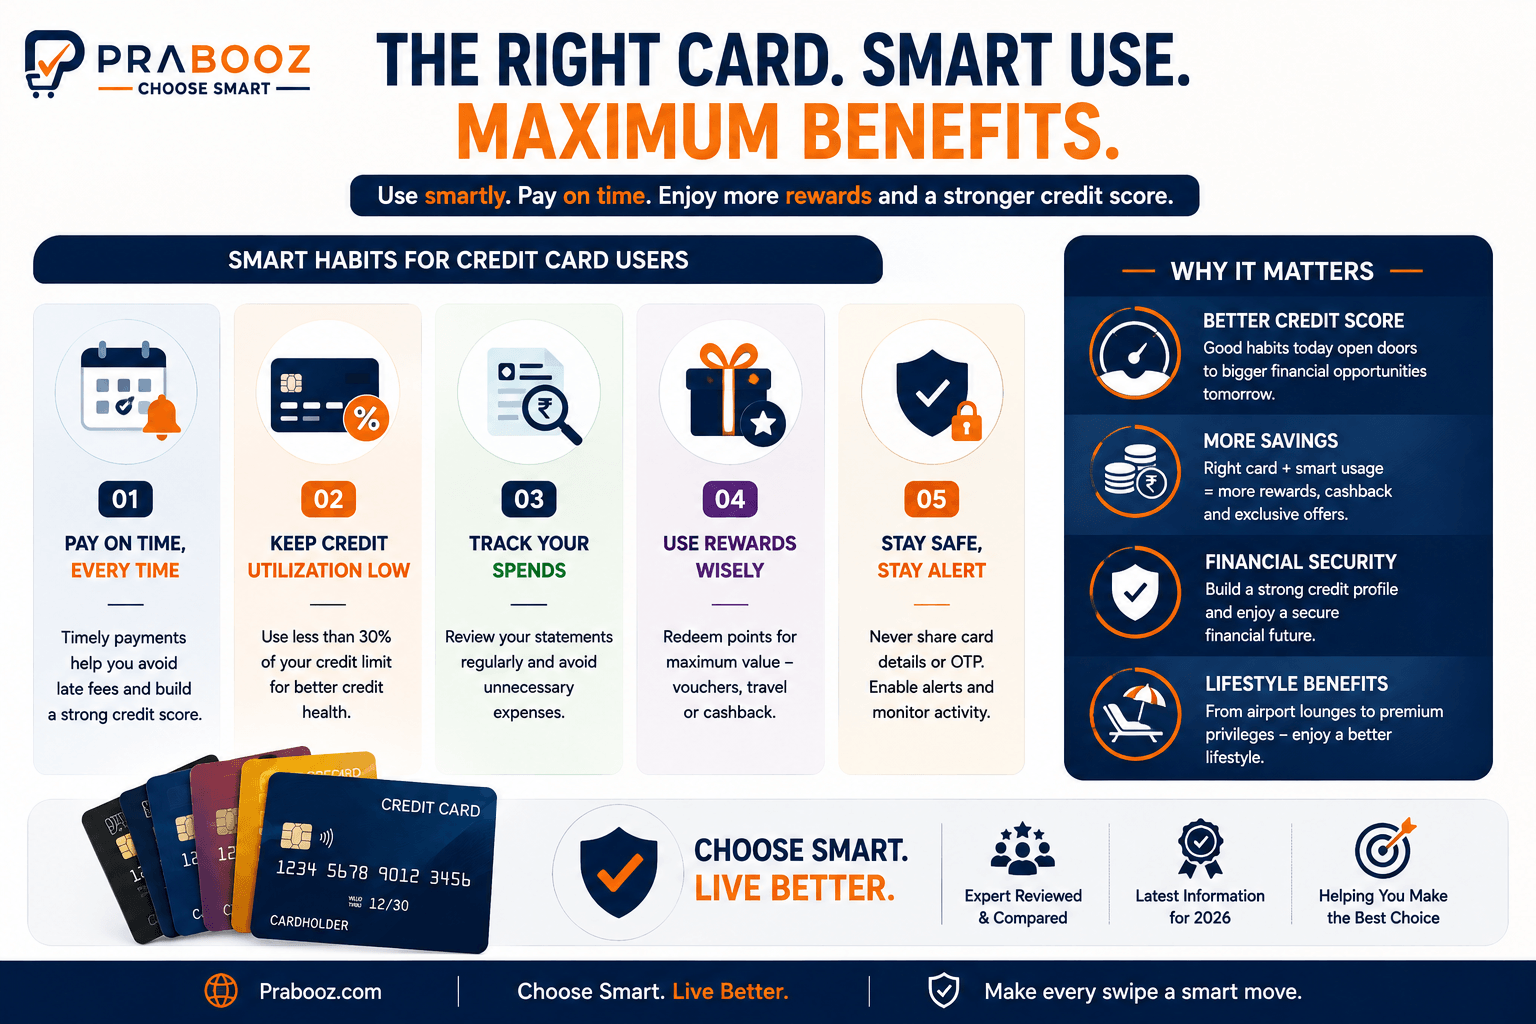
How to Use a Credit Card Smartly
A credit card can be a useful financial tool when you use it with discipline. The real value comes from enjoying rewards and convenience without allowing purchases, fees or interest charges to get out of control.
Pay Your Bill on Time
Try to pay your credit-card bill by the due date every month. If possible, pay the full amount due rather than carrying a balance from one month to the next.
This helps you avoid unnecessary interest costs and keeps your credit-card usage more manageable.
Keep Your Spending Under Control
A credit limit is not the same as your spending budget.
Use your card for purchases you can comfortably afford to repay. Don’t increase your spending simply because additional credit is available.
Keep Credit Utilisation in Mind
Your credit utilisation reflects how much of your available credit you are using.
Regularly using a very large portion of your credit limit may not be ideal for your credit profile. Keeping your utilisation under control can be a healthier approach to long-term credit management.
Use Rewards Wisely
Cashback, reward points, discounts and travel benefits can make a card more valuable—but they shouldn’t encourage unnecessary spending.
Don’t buy something you don’t need simply to earn rewards.
The best reward is the one you receive on spending you would have made anyway.
Track Your Transactions
Check your credit-card statements regularly and keep an eye on your recent transactions.
This helps you understand where your money is going, identify unexpected charges and notice potentially unauthorised transactions sooner.
Protect Your Card and Account
Keep your card details, PINs, passwords and OTPs private. Be cautious when clicking links or responding to messages claiming to be from your card issuer.
If you notice a transaction you don’t recognise, contact the issuer through its official customer-service channels promptly.
Detailed Credit Card Reviews
A quick comparison can help you shortlist credit cards, but the numbers alone don’t tell the whole story. A card’s annual fee, reward structure, spending conditions and additional benefits can make a significant difference to its actual value.
That’s why the following reviews look beyond headline rewards. For each card, we’ll consider what it costs, what it offers, where it can provide genuine value, and who should consider it.
We also highlight important limitations, because a credit card that looks attractive on paper may not be the right choice for every customer.
How We Review Each Card
For consistency, every detailed review will focus on the same practical factors:
- Annual fee and key charges
- Rewards, cashback or other benefits
- Important eligibility or spending conditions
- Main advantages
- Potential drawbacks
- Who should consider the card
- Who may want to look at alternatives
Frequently Asked Questions About Credit Cards in India
Which is the best credit card in India in 2026?
There is no single best credit card for everyone. The right card depends on your spending habits, preferred rewards, annual fee, travel needs and eligibility. A card that works well for an online shopper may not be the best choice for a frequent traveller.
Which credit card is best for cashback?
Cashback-focused cards can be useful for customers who prefer straightforward savings on eligible purchases. However, compare the cashback rate, spending categories, monthly or transaction limits, annual fee and exclusions before choosing one.
Is a credit card with no annual fee always better?
Not necessarily. A no-fee card can be excellent for someone who wants simple, low-cost credit, but a card with an annual fee may provide significantly more valuable rewards or benefits for the right user. The important thing is whether the benefits justify the cost.
Does using a credit card improve your credit score?
Responsible credit-card use can contribute positively to your credit profile over time. Paying bills on time, keeping credit utilisation under control and avoiding excessive applications are important habits.
Is it better to pay the full credit-card bill every month?
Yes. Paying the full amount due by the payment deadline helps you avoid revolving credit-card interest and keeps borrowing costs under control. Rewards should never be used as a reason to spend beyond what you can repay.
How many credit cards should I have?
There is no universal ideal number. One or two well-chosen cards may be enough for many people, while others may benefit from multiple cards for different spending categories. The key is being able to manage all payments and fees responsibly.
What should I check before applying for a credit card?
Check the annual and renewal fees, rewards structure, exclusions, eligibility requirements, interest charges, late-payment charges, credit limit, redemption conditions and other important terms.
A card can look attractive at first glance but become less valuable when you consider annual fees, reward limits, exclusions or other charges.
For general credit-card rules and consumer protections, see the [RBI’s Master Direction on Credit Card and Debit Card – Issuance and Conduct].
Can I apply for a credit card online?
Yes. Most major card issuers provide online application options. Before applying, check the issuer’s current eligibility criteria and official terms.
Final Verdict: Choose the Card That Fits You
Choosing a credit card in 2026 isn’t about finding the card with the biggest cashback number or the longest list of benefits.
It’s about finding the right balance between rewards, fees, benefits, spending habits and responsible repayment.
For one person, a cashback card may deliver the most practical value. For another, a travel card with lounge access may be worth the annual fee. Someone new to credit may have very different requirements from a high spender looking for premium benefits.
That’s why we haven’t treated one card as the universal winner.
Instead, this guide is designed to help you compare your options, understand the important conditions and choose based on the way you actually spend.
At Prabooz, our goal is simple: help you make smarter financial decisions without unnecessary complexity.
We compare products based on useful features, real-world value, costs and limitations — not simply on how attractive an offer looks.
Some links on Prabooz may eventually earn us a commission if you apply through them. However, that does not change our responsibility to present the advantages and disadvantages honestly.
Before applying for any credit card, always verify the issuer’s latest fees, eligibility requirements, rewards, exclusions and terms on the official website.
We hope this Best Credit Cards in India 2026: Complete Comparison Guide helps you compare your options and choose the right credit card for your spending needs.
Choose Smart. Live Better.
More Finance Guides from Prabooz
Credit Cards and Their Functions: Everything You Need to Know
Types of Credit Cards: Which One Is Right for You? (2026 Complete Guide)